What is Accounting profit?
Accounting profit is the residual reported after recognized revenues are reduced by explicit expenses under the relevant accounting framework and reporting period.
What is Economic profit?
Economic profit is a decision-making concept that subtracts explicit costs plus implicit opportunity costs from total revenue. It measures whether the chosen use of resources outperformed their next-best alternative.
Accounting profit vs Economic profit: comparison table
| Point of comparison | Accounting profit | Economic profit |
|---|---|---|
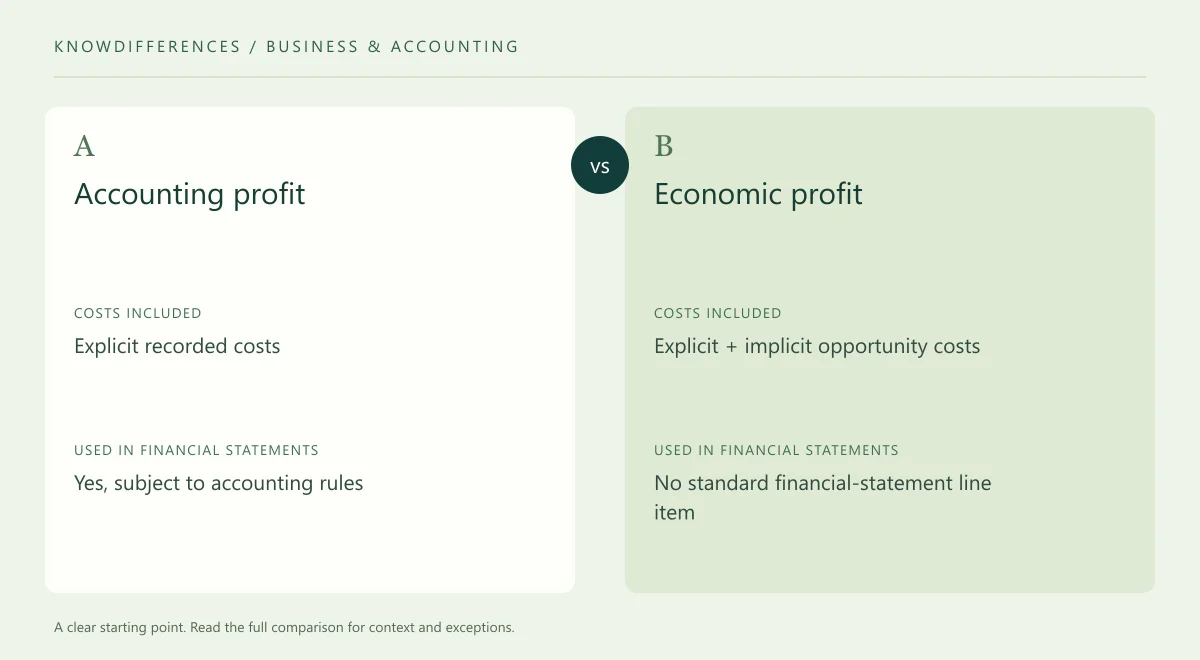
| Costs included | Explicit recorded costs | Explicit + implicit opportunity costs |
| Used in financial statements | Yes, subject to accounting rules | No standard financial-statement line item |
| Purpose | Measure reported business performance | Measure economic value above alternative use of resources |
| Can be positive when other is zero | Accounting profit can be positive while economic profit is zero/negative | Reflects required opportunity return |
| Owner labor/capital | Only recorded if expensed under accounting treatment | Includes foregone compensation/return as opportunity cost |
Similarities
- Both begin with business revenue and costs.
- Both are useful, but for different decisions.
- Both depend on the time period and assumptions used.
Practical examples
- A shop earns $120,000 after explicit expenses. If the owner gave up a $70,000 salary and $30,000 alternative return on invested capital, economic profit is only $20,000 even though accounting profit is $120,000.
How to distinguish them in practice
Identify whether the question is about operational records, valuation, reporting or economic analysis; the correct term follows from that context.
Common mistakes to avoid
- Using everyday meanings where accounting or economics assigns a more specific definition.
- Mixing quantity records, valuation records and financial-reporting concepts.
- Comparing figures prepared under different assumptions or time periods.
- Using the comparison as a substitute for the entity’s accounting policy or applicable reporting rules.
Simple example
Suppose a business earns 100,000 after all recorded expenses. The owner could earn 60,000 working elsewhere and could rent the owned building for 50,000. Accounting profit is 100,000, but after 110,000 of opportunity costs the economic profit is -10,000.
That does not mean the accounts are wrong; the two measures answer different questions.
Normal profit
Economists use normal profit to describe the return needed to keep resources in their current use. When economic profit is zero, the business is covering explicit costs and the owners’ opportunity costs.
In a competitive long-run equilibrium, firms may earn normal profit while accounting profit remains positive.
Why managers care
Economic thinking helps decide whether capital, property and owner effort would earn more elsewhere. Accounting profit remains essential for reporting and stewardship, but it does not automatically prove the current use is the best alternative.
Frequently asked questions
Can economic profit be negative while accounting profit is positive?
Yes, if opportunity costs exceed accounting profit.
Is economic profit shown on the income statement?
No. It is an analytical concept, not a standard financial-reporting subtotal.
What is normal profit?
In economics, normal profit is the return needed to keep resources in their current use; when economic profit is zero, the firm is covering explicit and implicit opportunity costs.
Why does economic profit matter?
It helps compare a business decision with the next-best use of the same capital, labor and time.
Bottom line
The most useful first check is costs included: Accounting profit — Explicit recorded costs; Economic profit — Explicit + implicit opportunity costs.
Sources and further reading
KnowDifferences Editorial Team
Independent explanations with definitions, practical examples and references. Read our editorial approach.